

Business owners often need additional funds at important stages of growth. You may want to purchase machinery, open another location, increase inventory, renovate your premises, manage seasonal working-capital requirements or consolidate existing business liabilities.
Once the requirement becomes clear, the next question is usually:
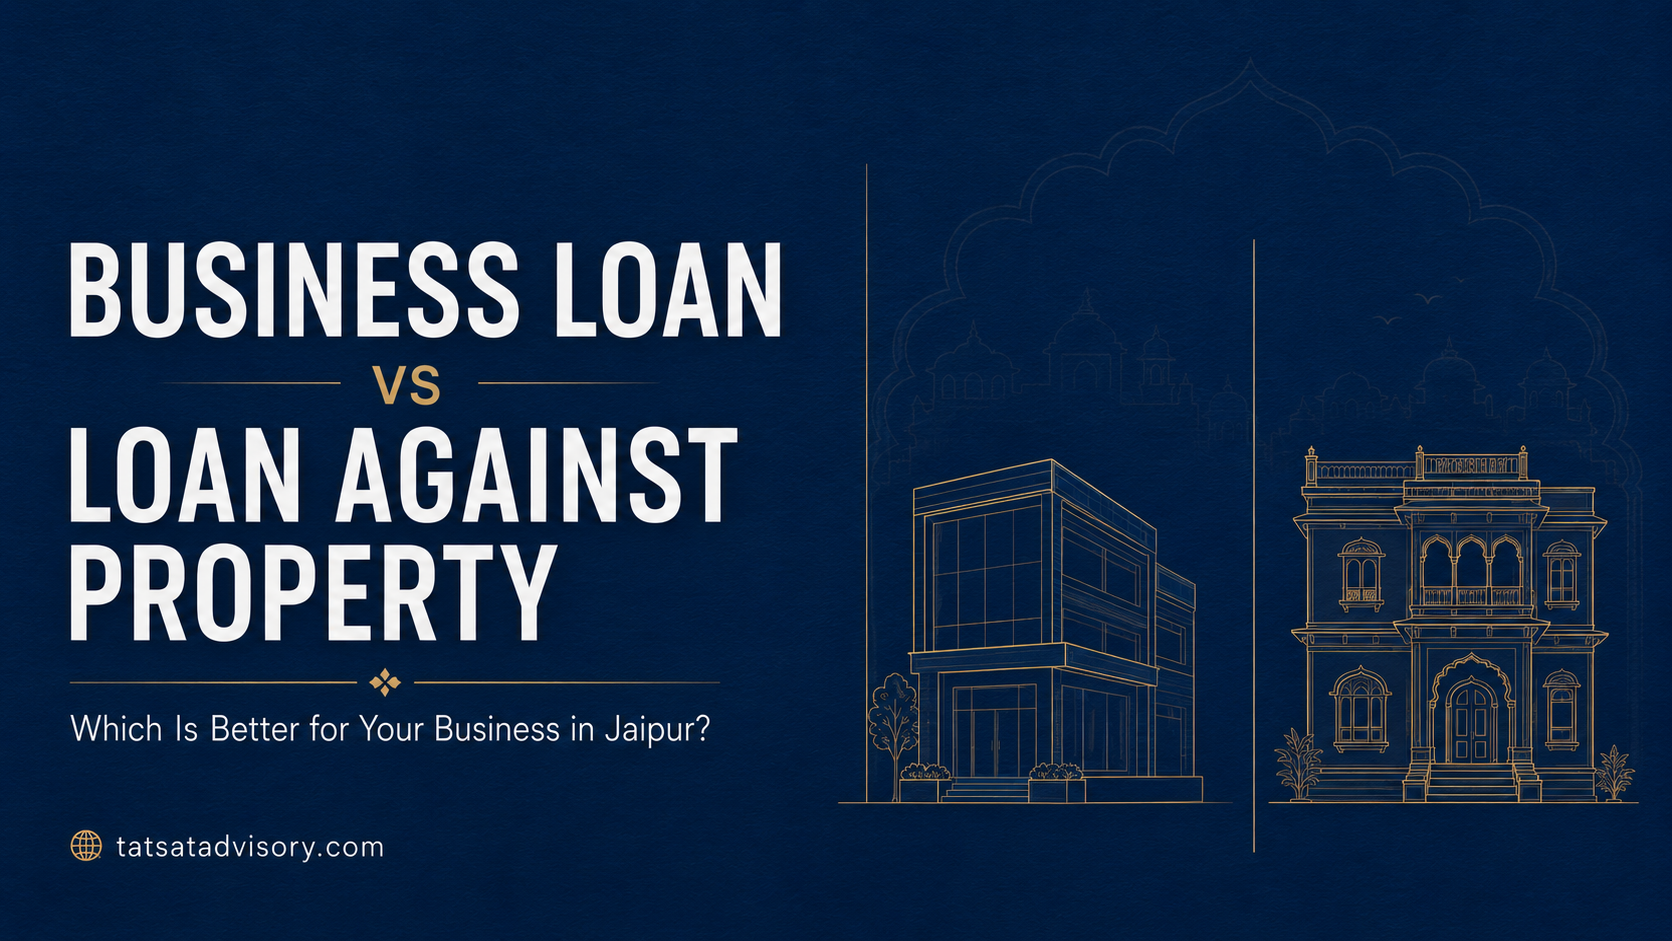
Should I apply for a business loan or take a loan against property?
Both options can provide funds for legitimate business requirements, but they are structured differently. A business loan may offer faster access without requiring property as collateral, while a Loan Against Property can be suitable for a larger or longer-term requirement backed by an eligible property.
The right choice depends on much more than the interest rate. The purpose of the loan, required amount, repayment capacity, business financials, property ownership and urgency must all be evaluated before applying.
This guide explains the difference between a business loan and a Loan Against Property for borrowers in Jaipur.
What Is a Business Loan?
A business loan provides funds for business-related requirements such as:
- Purchasing inventory or raw materials
- Managing cash-flow gaps
- Buying equipment
- Renovating business premises
- Expanding operations
- Meeting short- or medium-term business expenses
- Supporting marketing and distribution
- Consolidating eligible business liabilities
Many business loans are offered without requiring a residential or commercial property as collateral. In such cases, the lender evaluates the applicant primarily on the strength of the business, banking conduct, credit history, turnover, profitability and repayment capacity.
Depending on the lender and the borrower’s profile, secured business-loan options may also be available.
What Is a Loan Against Property?
A Loan Against Property, commonly called LAP, is a secured loan in which an eligible property is offered as collateral.
The property may be residential, commercial or industrial, subject to the lender’s policy, legal verification and technical valuation.
The borrower continues to own and use the property, but the lender creates a charge over it until the loan is repaid. If the borrower fails to repay according to the agreed terms, the lender may exercise its legal rights over the mortgaged property.
A Loan Against Property can be used for eligible business or personal requirements, subject to the lender’s policy and applicable restrictions.
Business Loan vs Loan Against Property: Key Differences
| Factor | Business Loan | Loan Against Property |
|---|---|---|
| Security | Often available without property collateral | Eligible property is mortgaged |
| Loan amount | Based mainly on business income, turnover and repayment capacity | Based on repayment capacity as well as the lender’s accepted value of the property |
| Processing | May be comparatively quicker when documentation is complete | Usually involves financial, legal and technical assessment |
| Repayment tenure | Often suited to short- or medium-term requirements | Longer repayment options may be available |
| Pricing | Unsecured lending may carry higher pricing | Secured nature may result in comparatively lower pricing for an eligible profile |
| Documentation | Business and financial documents are central | Business documents plus complete property papers are required |
| Risk to property | No property is mortgaged in an unsecured loan | Mortgaged property is at risk if repayment obligations are not met |
| Suitable for | Smaller, urgent or shorter-duration business requirements | Larger, structured or longer-term funding requirements |
These are general differences. The final terms always depend on the lender, product and individual applicant profile.
When Can a Business Loan Be the Better Option?
A business loan may be worth considering when:
1. You do not want to mortgage a property
Some business owners have an eligible property but prefer not to create a mortgage for a comparatively small or short-term requirement.
An unsecured business loan may allow them to raise funds without placing the property as collateral.
2. Your requirement is relatively urgent
Because a Loan Against Property requires legal and technical verification of the property, its processing can involve additional stages.
A well-documented business-loan application may sometimes be processed more quickly, subject to the lender’s procedures.
3. The funding requirement is short- or medium-term
If funds are required for inventory, seasonal demand, marketing or another business cycle, a business loan may be more suitable than creating a long-term charge over a property.
4. Your business has strong financials
A healthy turnover, stable profitability, satisfactory banking conduct and a sound repayment record may improve the strength of a business-loan proposal.
However, strong financials do not guarantee approval. Every lender applies its own eligibility and risk-assessment criteria.
5. The required amount does not justify mortgaging property
Creating a mortgage involves documentation, verification and related charges. For a smaller requirement, an unsecured option may be more practical despite potentially higher borrowing costs.
When Can a Loan Against Property Be the Better Option?
A Loan Against Property may be more appropriate when:
1. You need a larger amount
A property-backed loan may support a larger funding requirement, provided the borrower demonstrates sufficient repayment capacity and the property is acceptable to the lender.
The loan amount is not determined by property value alone. Income and cash flow remain essential.
2. You need a longer repayment period
A longer tenure can reduce the monthly repayment burden, although it may increase the total interest paid over the life of the loan.
The objective should not simply be to obtain the longest possible tenure. The repayment structure should match the business’s expected cash flow.
3. You want comparatively structured pricing
Because the loan is backed by property, LAP pricing may be more favourable than unsecured business-loan pricing for an eligible borrower.
However, the effective cost must be evaluated carefully. Processing fees, legal and valuation charges, insurance, documentation expenses, foreclosure conditions and other applicable costs should also be considered.
4. The fund requirement is for long-term business growth
A Loan Against Property may be suitable for planned expansion, substantial equipment purchases, renovation, acquisition of business premises or another long-term requirement.
Using a short-tenure loan for a long-term project can place unnecessary pressure on monthly cash flow.
5. You already own a clear and acceptable property
The property should generally have clear ownership, complete documents and marketability acceptable to the lender. Unauthorized construction, incomplete title history, ownership disputes or missing approvals can affect the proposal.
Do Not Choose Only by Comparing Interest Rates
Interest rate is important, but it is not the only factor that determines whether a loan is affordable.
Consider the following:
- Monthly EMI
- Repayment tenure
- Total interest outflow
- Processing and administrative charges
- Legal and technical expenses
- Insurance, if applicable
- Prepayment and foreclosure conditions
- Penal charges
- Flexibility of repayment
- Risk created by mortgaging property
- Expected return from using the borrowed funds
A lower-rate loan can still become expensive if it continues for a much longer period. Similarly, a higher-rate business loan may sometimes make commercial sense if it is used for a short, profitable business cycle and repaid responsibly.
The appropriate comparison is therefore not merely rate versus rate. It is:
Total borrowing cost versus the value and cash flow expected from the loan.
Documents Commonly Required for a Business Loan
Requirements vary between lenders, but applicants may generally be asked for:
- PAN and identity documents
- Address proof
- Business registration or constitution documents
- GST registration and returns, where applicable
- Income-tax returns
- Audited or certified financial statements
- Bank statements
- Existing loan statements
- Details of business vintage and operations
- Proof of business premises
- Provisional financials, where required
- Purpose and end-use details
A lender may request additional information depending on the business constitution, industry and requested amount.
Additional Documents for a Loan Against Property
Along with financial and identity documents, a LAP application generally requires property-related records, such as:
- Registered title documents
- Previous ownership documents forming the title chain
- Approved building plan, where applicable
- Property-tax receipts
- Mutation or revenue records, where relevant
- Possession or allotment documents
- Existing loan and closure documents, if the property was previously financed
- Society, authority or developer documents, where applicable
- Other legal and technical records requested by the lender
Submitting incomplete or inconsistent property papers can delay the process even when the applicant has adequate income.
Common Mistakes Jaipur Business Owners Should Avoid
Applying without calculating repayment capacity
The maximum eligible amount is not automatically the correct amount to borrow. The EMI must remain manageable even during slower business months.
Applying to multiple lenders simultaneously
Several applications made within a short period can create multiple credit enquiries. A more structured approach is to assess the profile first and then identify suitable lending options.
Hiding existing obligations
All running loans, credit facilities and repayment commitments should be disclosed accurately. Undisclosed liabilities can emerge during credit assessment and weaken the lender’s confidence.
Using short-term finance for a long-term project
If the investment will generate returns gradually, an excessively short repayment tenure can strain business cash flow.
Assuming property value guarantees a loan
A valuable property alone is not enough. Lenders also examine income, repayment ability, legal title, technical acceptability, credit history and the proposed use of funds.
Focusing only on the EMI
A smaller EMI achieved through a very long tenure may result in a higher total outflow. Both affordability and overall cost should be examined.
Sharing sensitive information carelessly
Never share banking passwords, card PINs or OTPs with anyone claiming to arrange a loan. Documents should only be shared through appropriate and trusted channels.
How to Decide Between the Two Options
Before choosing a product, answer these questions:
- How much funding does the business genuinely require?
- What is the exact purpose of the loan?
- How quickly are the funds needed?
- For how long will the funds remain deployed?
- What EMI can the business comfortably support?
- Is an eligible property available?
- Are its ownership and approval documents complete?
- Is the owner comfortable mortgaging it?
- What is the total cost under each option?
- What happens to repayment capacity if business income temporarily declines?
If the requirement is smaller, urgent and short-term, an unsecured business loan may be more practical.
If the amount is larger, the purpose is long-term and an eligible property with clear documents is available, a Loan Against Property may offer a more suitable structure.
The final decision should be based on the complete borrower profile rather than a single product feature.
How Tatsat Advisory Can Help
At Tatsat Advisory, we believe that the right loan begins with the right structure.
Before an application is submitted, the requirement should be examined carefully. Our support may include:
- Understanding the purpose and required loan amount
- Reviewing the applicant’s financial profile
- Evaluating repayment capacity
- Checking the available documentation
- Comparing suitable loan structures
- Reviewing EMI, tenure, charges and related conditions
- Assisting with financial projections where required
- Coordinating the application process
Our objective is to help Jaipur borrowers approach finance with clearer expectations and better preparation—not simply to submit an application without evaluating its suitability.
For assistance with a business loan or Loan Against Property in Jaipur, contact Tatsat Advisory at 433, Alankar Plaza, Vidhyadhar Nagar, Jaipur, or visit tatsatadvisory.com.
Frequently Asked Questions
Is a business loan better than a Loan Against Property?
Neither option is universally better. A business loan may suit an urgent or shorter-term requirement without property collateral. A Loan Against Property may suit a larger, longer-term requirement when an eligible property is available.
Can I use a Loan Against Property for business expansion?
A LAP may be used for eligible business requirements, subject to the lender’s policy, documented end use and applicable restrictions.
Does a valuable property guarantee LAP approval?
No. The lender also considers repayment capacity, income, credit history, existing liabilities, legal title and technical acceptability of the property.
Which option is processed faster?
An unsecured business loan may sometimes be processed more quickly because property verification is not required. Actual timelines depend on the lender, applicant profile and completeness of documents.
Can a self-employed person apply for both products?
Eligible self-employed individuals, proprietors, partners and companies may be considered, depending on the lender’s policies, business vintage, financial performance and repayment capacity.
Will a lower EMI always make LAP the better choice?
Not necessarily. A lower EMI may result from a longer tenure, which can increase total interest outflow. The total cost and risk of mortgaging property should also be evaluated.
Can Tatsat Advisory guarantee loan approval?
No responsible advisor can guarantee approval. The final decision, loan amount, pricing and terms remain entirely with the lender.